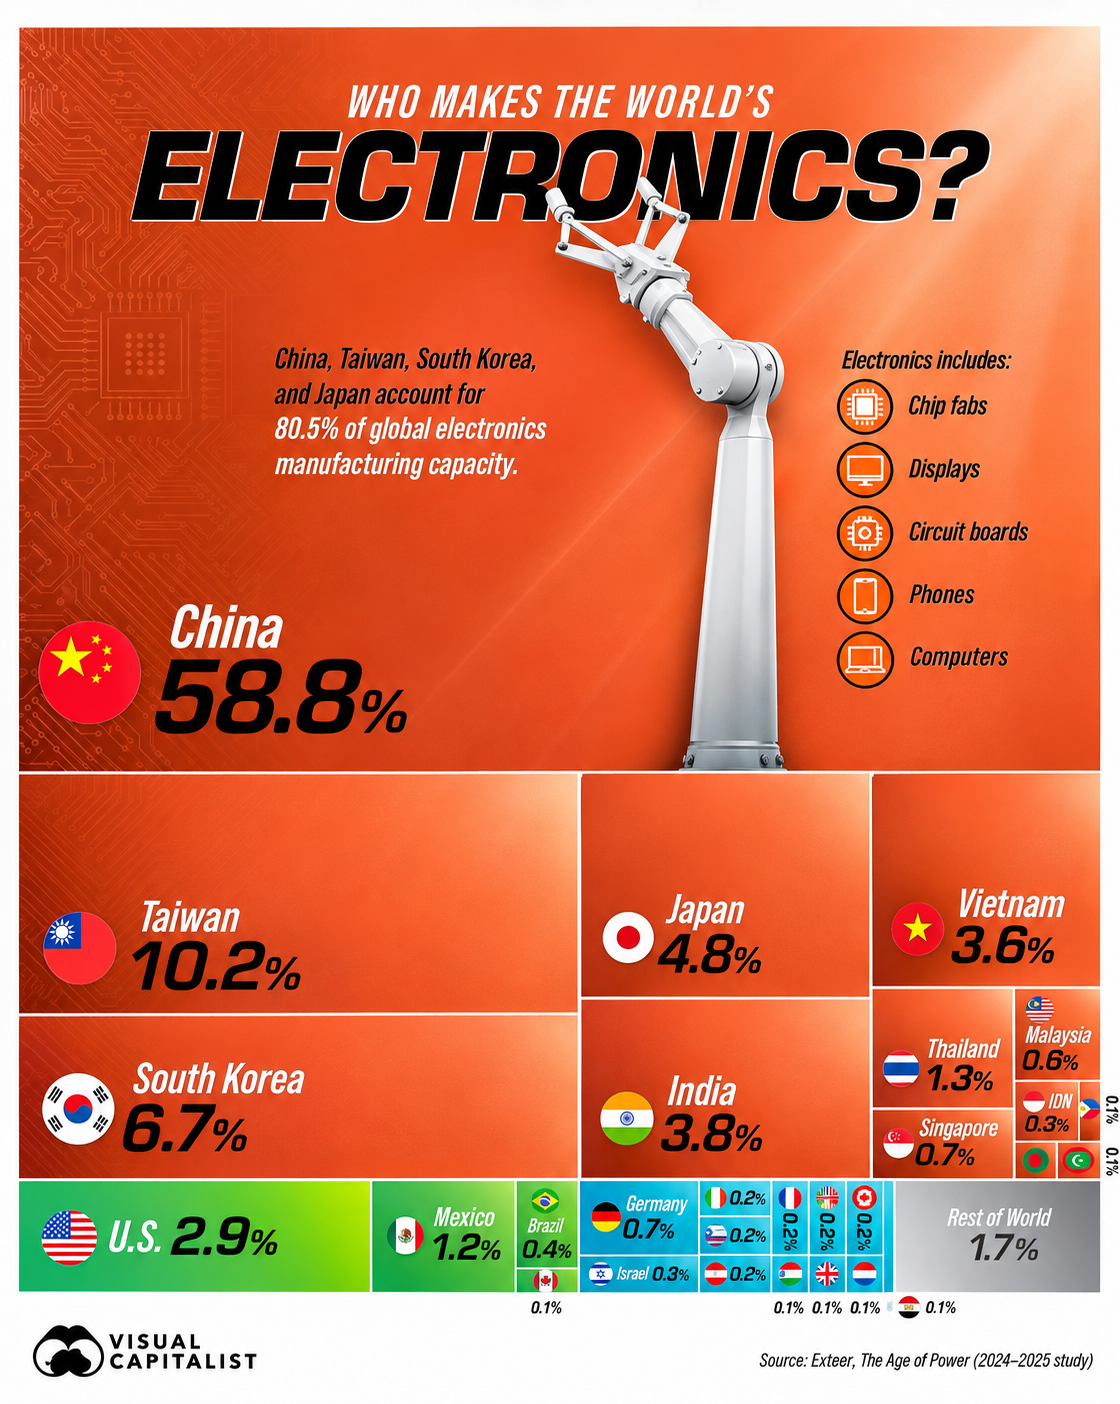
Global electronics manufacturing remains heavily concentrated in Asia, with four East Asian economies accounting for 80.5% of the world’s digital hardware manufacturing capacity, according to a 2024–25 analysis by Ember.
The findings, visualised by Visual Capitalist, highlight the concentration of global production across key electronics categories, including semiconductors, displays, printed circuit boards, smartphones and computers.
China Leads Global Digital Hardware Production
China dominates the global electronics manufacturing landscape, accounting for 58.8% of total digital hardware capacity. Its share is nearly six times that of second-ranked Taiwan, demonstrating the country’s significant position in global technology supply chains.
China’s manufacturing strength extends across several important hardware segments, making it a central supplier to industries ranging from consumer electronics and telecommunications to computing and industrial technology.
East Asia Accounts for More Than 80% of Global Capacity
The four leading countries are all located in East Asia and collectively represent 80.5% of global digital hardware capacity.
This concentration highlights the region’s importance to international manufacturers that depend on established electronics production networks, specialised suppliers and large-scale manufacturing infrastructure.
The findings also demonstrate how dependent global technology supply chains remain on a relatively small number of manufacturing locations.
India and Vietnam Strengthen Their Manufacturing Positions
India and Vietnam rank ahead of the United States in physical digital hardware manufacturing capacity, reflecting the growing importance of Asian manufacturing centres beyond China.
Their positions highlight the changing geography of electronics production as manufacturers continue to develop and diversify supply chains.
For the global electronics industry, this creates opportunities for new manufacturing partnerships while reinforcing the importance of production capacity, infrastructure and access to skilled labour.
Global Supply Chains Remain Concentrated
The analysis draws on Ember research using data from SEMI, DSCC, Prismark, Counterpoint Research, TrendForce, the International Energy Agency, BloombergNEF and the Global Wind Energy Council.
Its findings underline the strategic importance of electronics manufacturing to the global economy. As demand for semiconductors, computing equipment, smartphones and industrial electronics grows, the concentration of production capacity in Asia will remain an important consideration for manufacturers and technology supply chains worldwide.
